

What Is Crypto Lending?
Crypto lending is the process of lending digital assets to borrowers in exchange for interest, or borrowing assets by pledging cryptocurrency as collateral. It can happen through centralized companies, decentralized protocols, liquidity pools, or specialized lending arrangements.
At its simplest, the idea is remarkably similar to traditional lending. Someone has capital they don’t currently need, someone else needs liquidity, and the lending market connects the two.
The difference is that crypto lending replaces some traditional infrastructure with blockchain-based assets, smart contracts, tokenized debt positions, decentralized liquidity pools, and on-chain price oracles.
If you’ve been holding BTC, ETH, or another long-term asset and suddenly need $10,000, selling part of your position is not always attractive. You may want the cash, but you may also believe the asset will appreciate over the next few years. A collateralized crypto loan creates another possibility: borrow against the asset instead of immediately selling it.
That doesn’t make the strategy risk-free. In fact, the collateral can be liquidated if its value falls far enough. But conceptually, crypto lending gives you access to liquidity while separating the act of borrowing cash from the act of selling an investment.
On the lending side, the opposite opportunity exists. If you have assets sitting idle, you can supply them to a lending market and potentially earn interest from borrowers. In Aave, for example, supplied assets enter liquidity pools, while users receive interest-bearing aTokens representing their supplied positions. (aave.com)
That creates two sides of the market:
- Borrowers want liquidity without necessarily selling their assets.
- Lenders or liquidity providers want their idle capital to generate a return.
And once you understand those two sides, most of crypto lending becomes much easier to understand.
The Fundamental Mechanism: Why Borrow Instead of Sell?
Let’s say you own $100,000 worth of ETH.
You need $30,000 to fund a business, pay an expense, or simply access liquidity.
You have two obvious choices.
You could sell $30,000 of ETH. That’s simple, but you’ve reduced your ETH exposure. If ETH doubles later, you no longer participate in the full upside because you sold part of your position.
Or you could deposit ETH as collateral and borrow $30,000 worth of stablecoins.
Now you still have economic exposure to your ETH, but you have created a debt obligation against it.
That’s the fundamental attraction of crypto-backed borrowing.
The trade-off is that you are effectively converting price exposure into leveraged exposure. If ETH rises, keeping the collateral may work beautifully. If ETH falls sharply, however, the value of your collateral can approach the liquidation threshold.
This is why experienced borrowers don’t ask only, “How much can I borrow?”
They ask:
How much can I borrow while still having enough room to survive a serious market drawdown?
That difference in mindset matters.
Aave, one of the largest DeFi lending protocols, describes its core model as supplying assets to earn interest and borrowing against supplied collateral. Its current documentation also emphasizes that supplied assets can be used as collateral for borrowing. (aave.com)
Crypto Lending Taxonomy: DeFi, CeFi, and Alternative Models
“Crypto lending” isn’t one single product.
It’s better understood as an umbrella term covering several different models.
| Model | How it works | Typical risk |
|---|---|---|
| DeFi lending | Smart contracts connect suppliers and borrowers | Smart-contract, oracle, liquidation risk |
| CeFi lending | A centralized company manages lending and custody | Counterparty, custody, insolvency risk |
| Peer-to-peer lending | Borrower and lender are matched directly | Counterparty and default risk |
| Peer-to-pool lending | Users supply liquidity to a shared pool | Smart-contract and utilization risk |
| Over-collateralized lending | Borrower posts more collateral than the loan | Liquidation risk |
| Under-collateralized lending | Creditworthiness supplements collateral | Credit/default risk |
| Flash loans | Borrowed liquidity must be returned within one transaction | Smart-contract and execution risk |
The category matters because the word “lending” can hide radically different risk profiles.
A USDC deposit into a DeFi liquidity pool is not economically identical to handing BTC to a centralized lending company. Both may advertise an APY, but the source of that yield and the party carrying the risk can be completely different.
How Crypto Lending Works: Step-by-Step Workflow

A typical DeFi lending transaction looks something like this:
Borrower deposits collateral → protocol values collateral → borrowing capacity is calculated → loan is issued → interest accrues → borrower repays → collateral becomes withdrawable.
The entire process can be automated by smart contracts.
Aave’s documentation describes its markets as non-custodial infrastructure where users supply assets and can borrow against supplied collateral, while interest rates adjust according to market utilization. (aave.com)
Let’s walk through what actually happens.
For Borrowers: Unlocking Liquidity
Wallet Connection and Collateral Deposit
You first connect a compatible Web3 wallet to the lending protocol.
Depending on the market, your collateral might be ETH, WBTC, WETH, stablecoins, liquid-staking tokens, or another supported asset.
Suppose you deposit $50,000 worth of ETH.
The protocol doesn’t simply say, “You have $50,000, so you can borrow $50,000.”
That would obviously be dangerous.
Instead, each collateral asset has risk parameters determining how much borrowing power it provides.
Aave’s reserve configuration includes parameters such as LTV, liquidation threshold, and liquidation bonus, and those values can differ between assets and markets. (aave.com)
LTV Verification Through Price Oracles
The protocol needs to know what your collateral is worth.
That’s where price oracles enter the picture.
If ETH is trading at $3,000 and you deposit 10 ETH, the protocol needs a reliable reference price before calculating your borrowing capacity.
This sounds straightforward until you remember that blockchains don’t automatically know what ETH is trading for on external markets.
Oracle infrastructure bridges that gap.
Chainlink is one of the most widely used oracle networks in DeFi, while Pyth provides real-time financial market data for smart-contract applications across more than 100 blockchains. (Pyth Developer Hub)
The exact oracle architecture varies by protocol, and that matters because an inaccurate or delayed price can affect collateral valuations and liquidations.
Receive Stablecoins or Other Assets
Once your borrowing capacity is established, you can borrow an available asset.
Stablecoins such as USDC or USDT are particularly useful because they let you extract relatively stable liquidity from a volatile collateral asset.
For example:
$50,000 ETH collateral → $25,000 USDC debt
You still own the ETH, but you now owe the protocol $25,000 plus accrued borrowing costs.
You can potentially use the USDC outside the protocol, depending on the market’s rules and the assets supported by the protocol.
Interest Accumulates Until Repayment
The debt isn’t static.
Interest accrues according to the market’s borrowing rate.
In variable-rate lending markets, that rate can change as supply and demand change.
Aave explains that its interest rates respond to utilization: as a larger percentage of available liquidity gets borrowed, borrowing rates generally rise, while supplier returns also increase with utilization. (aave.com)
Eventually, you repay the borrowed amount plus accumulated interest.
If your position remains healthy, your collateral can then be withdrawn.
For Lenders: Earning Passive Yield on Idle Crypto
The other side is arguably even simpler.
You deposit an asset into a lending market.
The protocol makes that liquidity available to borrowers.
Borrowers pay interest.
Part of that interest flows back to suppliers, subject to the protocol’s rules, fees, reserves, and incentives.
On Aave, suppliers receive aTokens representing their supplied assets. Aave’s documentation explains that aTokens are minted when users supply assets and that their balances incorporate the yield generated by those positions. (aave.com)
This creates a useful mental model:
Your crypto becomes productive capital rather than simply sitting idle in your wallet.
However, “passive” shouldn’t be confused with “risk-free.”
You are still exposed to protocol design, smart contracts, asset liquidity, governance parameters, and potentially the underlying market.
And if you’re chasing an unusually high APY, you should immediately ask where that yield is coming from.
CeFi vs. DeFi Crypto Lending
This is one of the most important distinctions in the entire crypto lending market.
With CeFi lending, a centralized company sits between you and the borrower or investment strategy.
With DeFi lending, smart contracts and blockchain infrastructure perform much of the same function.
Neither model is automatically safer.
They simply move risk around.
| Feature | CeFi Lending | DeFi Lending |
|---|---|---|
| Execution | Centralized infrastructure | Smart contracts |
| Custody | Usually third-party custody | Often wallet-controlled interaction |
| Transparency | Depends on company disclosures | Much of the activity can be on-chain |
| Counterparty | Centralized company | Protocol, smart contracts, liquidity providers |
| Main risks | Insolvency, custody, mismanagement | Bugs, oracle failures, exploits |
| Liquidity | Controlled by provider | Determined by protocol markets |
| Interest model | Company-defined | Often algorithmic |
| Examples | Nexo and similar services | Aave, Compound, Morpho |
A useful historical warning comes from the collapse and regulatory problems surrounding centralized crypto lending.
In 2022, the U.S. Securities and Exchange Commission announced that BlockFi agreed to pay $100 million in penalties and stop offering its retail Interest Account product in the United States as part of the settlement. The SEC’s order also addressed BlockFi’s activities involving loans of crypto assets to institutional borrowers. (SEC)
The lesson isn’t that every centralized lender is unsafe.
The lesson is much simpler:
When you give a centralized company custody of your crypto, you are trusting its balance sheet, risk controls, counterparties, and management.
That’s a fundamentally different trust assumption from depositing assets into an open smart-contract protocol.
DeFi changes the trade-off rather than eliminating it. You may reduce reliance on a centralized intermediary, but now you have to care much more about smart-contract security, oracle design, governance, liquidity parameters, and blockchain infrastructure.
Core Parameters and Risk Metrics: LTV, Liquidation Threshold, and Health Factor
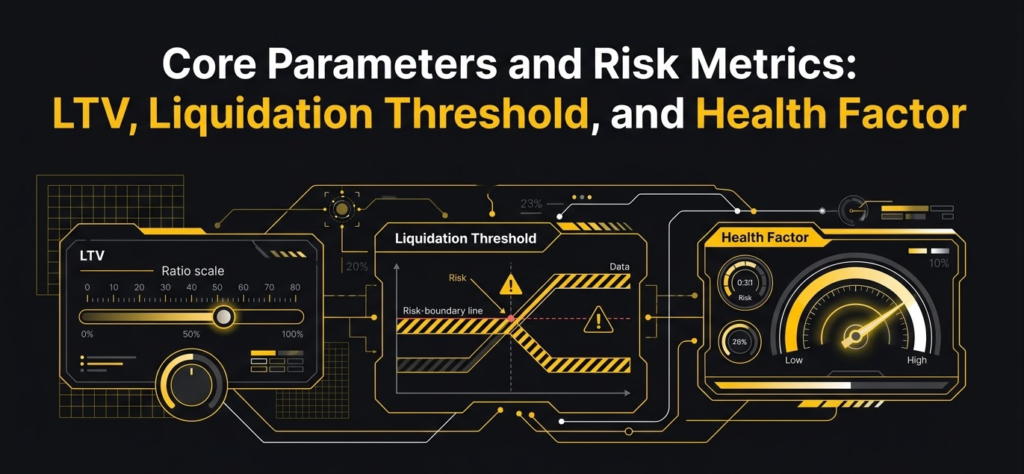
If you want to use crypto lending seriously, there are four terms you should understand before depositing meaningful capital:
- LTV
- Liquidation threshold
- Liquidation penalty or bonus
- Health factor
They sound technical, but once you connect them to a real position, they become much easier.
Understanding Loan-to-Value and Liquidation Thresholds
Loan-to-Value (LTV) measures how much you can borrow relative to the value of your collateral.
If you have $100,000 of collateral and the protocol allows a 75% LTV, your theoretical maximum borrowing capacity is $75,000.
But that doesn’t mean borrowing $75,000 is a smart idea.
The LTV is a borrowing limit, not a recommended safety level.
If your collateral falls in value, your effective LTV rises.
For example:
| Collateral | Debt | Effective LTV |
|---|---|---|
| $100,000 | $40,000 | 40% |
| $100,000 | $60,000 | 60% |
| $100,000 | $75,000 | 75% |
| $80,000 | $60,000 | 75% |
| $60,000 | $60,000 | 100% |
Notice what happens in the final rows.
You didn’t borrow more money.
Your collateral simply became less valuable.
That’s why market volatility can turn a seemingly comfortable position into a liquidation candidate surprisingly quickly.
The liquidation threshold is related but not identical to the maximum initial LTV. It represents the point at which a borrow position becomes eligible for liquidation under the protocol’s risk parameters.
Aave explains that the health factor measures the safety of a borrow position and that a health factor below 1 indicates liquidation risk. (aave.com)
The Health Factor Formula
A simplified version of the health factor can be written as:
HF=∑(Collateral Amounti×Oracle Pricei×Liquidation Thresholdi)∑(Borrowed Amountj×Oracle Pricej)HF = \frac{ \sum(\text{Collateral Amount}_i \times \text{Oracle Price}_i \times \text{Liquidation Threshold}_i) }{ \sum(\text{Borrowed Amount}_j \times \text{Oracle Price}_j) }
The intuition is more important than memorizing the equation.
If your collateral becomes more valuable, your health factor generally improves.
If your debt increases, your health factor generally deteriorates.
If the collateral price falls, your health factor falls.
Aave gives a simple example in which $10,000 of ETH collateral with an 80% liquidation threshold and $6,000 of debt produces a health factor of 1.333. (aave.com)
The practical interpretation is:
- HF > 1: position is generally above the liquidation boundary.
- HF approaching 1: risk is increasing sharply.
- HF ≤ 1: the position can become eligible for liquidation.
I personally wouldn’t treat 1.01 as “safe” simply because it is technically above 1.
Crypto can move far faster than you expect.
A more conservative borrower may deliberately maintain a substantial buffer above the liquidation threshold rather than constantly operating at maximum borrowing capacity.
Types of Crypto Loans
Crypto lending isn’t limited to the standard “deposit BTC, borrow USDC” structure.
There are several different forms.
Over-Collateralized Loans
This is the dominant model in permissionless DeFi.
You provide collateral worth more than the amount you borrow.
For example:
$100,000 ETH collateral → $50,000 USDC loan
The protocol doesn’t need to know your salary, credit score, or employment history.
Instead, it relies on collateral and automated risk parameters.
Aave describes its lending markets as facilitating overcollateralized borrowing, with supplied assets serving as collateral for loans. (aave.com)
This works particularly well on public blockchains because collateral can be monitored continuously.
The downside is capital inefficiency.
If you need $50,000, you might need to lock significantly more than $50,000 worth of assets.
Under-Collateralized and Credit-Based Lending
Under-collateralized lending tries to solve that capital-efficiency problem.
Instead of demanding that every loan be heavily overcollateralized, lenders may consider:
- borrower reputation;
- institutional identity;
- credit history;
- off-chain legal agreements;
- business cash flows;
- third-party attestations;
- portfolio information.
This is closer to traditional credit markets.
The challenge is obvious: how do you enforce a real-world debt obligation on a blockchain?
Smart contracts are excellent at enforcing rules over digital assets.
They’re much less powerful when the borrower simply disappears with the money.
That’s why under-collateralized crypto lending often introduces additional legal or off-chain infrastructure.
And this is precisely where you should be skeptical of simplistic claims that “DeFi eliminates credit risk.”
It doesn’t.
It mostly eliminates or reduces certain intermediaries in some lending designs.
Flash Loans
Flash loans are one of the strangest and most interesting concepts in DeFi.
You can borrow a large amount of capital without providing conventional collateral upfront, but the entire loan must be repaid within the same transaction.
Aave describes flash loans as “one block borrows” where the borrowed amount plus the applicable fee must be returned before the transaction completes; if repayment conditions aren’t satisfied, the transaction reverts. (aave.com)
That sounds impossible if you’re thinking about traditional finance.
But blockchains give smart contracts atomic transaction execution.
A flash-loan transaction might effectively do this:
Borrow $10 million
        ↓
Execute arbitrage
        ↓
Swap Asset A → Asset B
        ↓
Sell Asset B elsewhere
        ↓
Repay $10 million + fee
        ↓
Keep the arbitrage profit
If the transaction cannot repay the loan, the entire transaction can fail.
Aave lists arbitrage and liquidation-related operations among the use cases for flash loans. (aave.com)
Flash loans are therefore not really consumer loans.
They’re more like temporary programmable liquidity for sophisticated on-chain transactions.
Liquidation Mechanics and Oracle Vulnerabilities
Liquidation is where the theoretical mathematics of crypto lending becomes very real.
If your collateral loses enough value, the protocol needs to protect lenders.
Otherwise, borrowers could owe $100,000 while holding only $50,000 of collateral.
That’s unacceptable for an over-collateralized lending system.
How Automated Liquidations Work
Once a position becomes eligible for liquidation, an external participant called a liquidator can often repay some or all of the borrower’s debt in exchange for a portion of the collateral, including an incentive or liquidation bonus.
Aave explicitly describes liquidations as permissionless: network participants can repay eligible debt and receive collateral with a liquidation bonus. (aave.com)
That creates a competitive market around liquidations.
Professional liquidators monitor blockchain positions and oracle prices continuously. When a position becomes liquidatable, they can submit transactions to capture the available liquidation incentive.
For the borrower, this can feel brutal.
You might wake up and discover that part of your ETH has disappeared because the protocol automatically sold collateral to cover your debt.
From the protocol’s perspective, however, the liquidation is doing exactly what it was designed to do: protecting the solvency of the lending pool.
Why Liquidation Penalties Matter
The liquidation penalty or bonus compensates the liquidator for taking execution and market risk.
The exact percentage varies by protocol, asset, and market configuration.
So I would avoid treating a generic 5%–15% liquidation penalty as a universal DeFi rule. The actual parameter is protocol-specific and can change through governance.
Aave, for example, exposes liquidation bonus as a reserve-level configuration parameter rather than imposing one universal number across every asset. (aave.com)
This is an important detail when you’re comparing protocols.
Always check the actual market you’re borrowing against.
Price Oracles and Flash-Loan Exploit Vectors
Oracles are one of the most sensitive parts of a lending protocol.
If the protocol thinks ETH is worth $3,000 when the real market price is $2,500, borrowers and liquidators can potentially exploit that discrepancy.
This is why mature protocols use specialized oracle architectures instead of simply reading a single exchange’s spot price.
Pyth currently describes its price feeds as real-time financial market data sourced from more than 120 first-party providers and available across more than 100 blockchains. (Pyth Developer Hub)
Its current Pyth Core documentation also describes on-chain price updates with frequencies of up to every 400 milliseconds. (Pyth Developer Hub)
Chainlink similarly provides decentralized market-data infrastructure intended for smart-contract applications, including financial markets.
But an oracle isn’t automatically immune to manipulation.
Attackers have historically attempted to exploit thin liquidity, stale prices, low-quality price sources, and poorly designed oracle integrations.
Flash loans can amplify these attacks because they provide enormous temporary capital without requiring the attacker to own the full amount upfront.
The key distinction is that a flash loan itself isn’t the vulnerability.
The vulnerability is usually somewhere in the surrounding pricing or protocol logic.
Why Borrowing Crypto Is Not Always a Taxable Event?
This section needs an important correction to the simplified premise in the outline.
It is tempting to say:
“Borrowing against crypto is not taxable because a loan isn’t income.”
That can be directionally true for ordinary loan proceeds in some jurisdictions, but you should never turn that into a universal crypto tax rule.
Tax treatment depends on the country, the structure of the loan, what happens to the collateral, whether the collateral is actually transferred, whether it is later liquidated, and how the tax authority characterizes the transaction.
In the United States, the IRS generally treats genuine loan proceeds as not being included in gross income because the borrower has an obligation to repay. Its guidance on loan proceeds states that receipt of loan proceeds is generally not included in gross income, although debt forgiveness can create taxable income. (Cơ Quan Thuế IRS)
That doesn’t automatically mean every crypto lending transaction is tax-neutral.
A taxable event could potentially arise when you:
- sell collateral;
- exchange one asset for another;
- have collateral liquidated;
- receive lending rewards or interest;
- repay through a transaction that constitutes a disposal under local rules.
The UK demonstrates why you should be especially careful with blanket statements.
HMRC’s cryptoasset guidance has historically treated certain DeFi lending arrangements as potentially involving disposals depending on beneficial ownership and the contractual structure. (GOV.UK)
More recently, HMRC published a July 2026 policy measure that proposes specific “no gain, no loss” treatment for certain cryptoasset lending and borrowing arrangements, effectively deferring some Capital Gains Tax consequences until an economic disposal. (GOV.UK)
That’s a perfect example of why crypto tax articles become outdated so quickly.
The broader lesson is:
Borrowing can be tax-efficient in some circumstances, but “crypto loans are tax-free” is not a safe universal statement.
The EU is even less suitable for a single blanket answer because member states apply their own tax rules to cryptoassets and financial transactions.
So if you’re using crypto lending as part of a serious investment or tax strategy, treat the tax section of a generic crypto article as educational information-not individualized tax advice.
Evaluating Yield: Organic Yield vs. Token Emissions
Now let’s flip the perspective.
What if you aren’t borrowing?
What if you want to lend?
This is where crypto lending gets particularly interesting because platforms can advertise surprisingly high APYs.
But not all yield is created equal.
Real or Organic Yield
The cleanest form of lending yield comes from borrower interest.
You supply USDC.
Someone borrows USDC.
They pay interest.
You receive a portion of that interest.
This is economically intuitive.
Aave explains that supplier rates are funded by borrowing activity and that utilization affects the interest-rate relationship between borrowers and suppliers. (aave.com)
When demand for borrowing increases, lending yields can rise.
When demand falls, yields can decline.
This is why a lending APY should never be viewed as a permanent salary.
It’s a market price.
Utilization Rate
A simplified utilization ratio can be expressed as:
U=Total BorrowedTotal SuppliedU = \frac{\text{Total Borrowed}}{\text{Total Supplied}}
Imagine a pool has:
- $100 million supplied;
- $50 million borrowed.
Utilization is 50%.
If borrowers take another $30 million:
- $80 million is borrowed;
- $100 million is supplied.
Utilization becomes 80%.
As utilization increases, protocols may raise borrowing rates to encourage more supply and discourage excessive borrowing.
Aave explicitly uses utilization-based interest-rate curves, including a steeper response after a target “kink” to help protect available liquidity. (aave.com)
This mechanism is one of the most important pieces of DeFi lending economics.
Emission-Based Yield
The other type of yield comes from incentives.
A protocol might offer:
- lending interest;
- governance tokens;
- liquidity-mining rewards;
- bonus incentives.
Suddenly, an asset might advertise a 12% APY even though borrowers are only paying 5%.
Where does the other 7% come from?
Potentially from token emissions.
That doesn’t automatically make the strategy bad.
Token incentives can be useful for bootstrapping a new market.
But you should separate:
5% organic borrower yield + 7% token incentives
from:
12% sustainable borrower yield.
They are not the same thing.
If the reward token loses 80% of its value, that “12% APY” can look very different in practice.
This is why I always recommend looking beyond the big APY number and asking:
Who is actually paying this yield?
If the answer is “borrowers,” you have one type of economic engine.
If the answer is “the protocol is printing tokens,” you have another.
Primary Risks and Mitigation Strategies
Crypto lending can be extremely useful, but you need to understand the risk stack.
There isn’t one single “crypto lending risk.”
There are several.
Smart Contract Risk
DeFi lending protocols are software.
Software can contain bugs.
Even audited contracts can theoretically have vulnerabilities.
The best mitigation is to favor protocols with:
- long operating histories;
- public source code;
- reputable audits;
- active bug-bounty programs;
- transparent governance;
- clearly documented risk parameters.
But don’t treat an audit as an insurance policy.
An audit means qualified researchers reviewed a particular codebase under particular assumptions.
It doesn’t mean the protocol can never be exploited.
Market Volatility Risk
This is the risk most borrowers encounter first.
You borrow against ETH.
ETH falls.
Your collateral becomes worth less.
Your LTV rises.
Your health factor falls.
Eventually, liquidation becomes possible.
The easiest mitigation is to avoid borrowing at the maximum available LTV.
If a protocol theoretically lets you borrow 75% of your collateral, that doesn’t mean you should.
I would rather have a boring health factor with a large buffer than squeeze every last dollar out of a loan and spend the next month staring at liquidation alerts.
Oracle Risk
Oracle failures can create serious problems because lending protocols rely on price data for collateral valuation.
Use protocols with well-documented oracle systems and understand which oracle provider supports each market.
Pyth’s current documentation, for example, explains that its price feeds provide real-time data and that the network supports both push and pull mechanisms for on-chain consumption. (Pyth Developer Hub)
The details matter because “uses Pyth” or “uses Chainlink” alone doesn’t tell you exactly how the protocol consumes the data.
Counterparty and Custodial Risk
This is particularly important for CeFi.
If a company holds your crypto, you’re trusting that company.
It may lend your assets to other entities, invest them, use them as collateral, or otherwise deploy them according to its business model.
That doesn’t automatically make the company malicious.
It means you need to understand what you’re actually buying.
The BlockFi case is a useful reminder that centralized crypto yield products can carry regulatory and balance-sheet risks that aren’t obvious from the advertised APY alone. (SEC)
Liquidity Risk
A protocol may have $100 million in total deposits but not necessarily $100 million immediately available for withdrawal.
Much of the liquidity could already be borrowed.
This matters during market stress.
Aave’s documentation explicitly notes that withdrawal availability can depend on unborrowed liquidity and the user’s collateral position. (aave.com)
So when you supply assets, don’t only look at total TVL.
Look at available liquidity and utilization.
A More Conservative Borrowing Strategy
If you are using crypto lending for real liquidity rather than speculation, a conservative approach might look like this:
- Borrow significantly below the maximum LTV.
- Keep a stablecoin reserve outside the protocol.
- Monitor your health factor.
- Set price alerts for your collateral.
- Avoid concentrating the entire collateral position in one volatile asset.
- Understand the liquidation process before borrowing.
- Know how to repay or add collateral quickly.
- Don’t rely on token incentives to justify excessive leverage.
The goal isn’t to maximize the amount you can borrow.
The goal is to make the loan survivable.
Frequently Asked Questions
What is crypto lending and how does it work?
Crypto lending is the process of lending digital assets to borrowers in exchange for yield or borrowing digital assets by using cryptocurrency as collateral.
In DeFi, users typically deposit assets into smart-contract-controlled liquidity markets. Borrowers provide collateral, receive another supported asset, and pay interest over time. Protocols use price oracles and risk parameters such as LTV and liquidation thresholds to determine whether positions remain solvent. Aave, for example, uses supplied assets as collateral and dynamically adjusts interest rates according to market utilization. (aave.com)
Why do people borrow against crypto instead of selling?
The main reason is to access liquidity while maintaining exposure to the underlying asset.
For example, instead of selling $50,000 of ETH to obtain $50,000 in cash, an investor might use ETH as collateral and borrow stablecoins.
If ETH appreciates, the investor continues to hold the collateral.
But there is a critical downside: if ETH falls enough, the collateral can be liquidated.
So borrowing against crypto effectively trades immediate asset ownership for a leveraged debt position.
What happens if my crypto collateral drops in price?
Your collateral becomes less valuable relative to your outstanding debt.
As a result, your LTV increases and your health factor generally falls.
If the position crosses the protocol’s liquidation boundary, liquidators can repay debt and receive collateral according to the protocol’s liquidation rules. Aave describes this process as a permissionless mechanism designed to restore the health of risky positions and protect protocol solvency. (aave.com)
You may be able to avoid liquidation by:
- repaying part of the loan;
- adding more collateral;
- reducing debt;
- selling part of the collateral before the protocol liquidates it.
What is the difference between CeFi and DeFi crypto lending?
CeFi lending relies on a centralized company to manage custody, lending, risk management, and often the user relationship.
DeFi lending uses blockchain-based smart contracts to automate much of that process.
The major trade-off is custodial risk versus protocol risk.
With CeFi, you may face company insolvency, custody problems, opaque balance sheets, and counterparty exposure.
With DeFi, you face smart-contract exploits, oracle failures, governance risk, liquidation mechanics, and blockchain infrastructure risk.
Neither model eliminates risk.
They simply distribute it differently.
What is a flash loan in crypto?
A flash loan is a form of uncollateralized, atomic borrowing where the borrowed assets must be returned within the same blockchain transaction.
Aave describes flash loans as one-block borrowing in which the amount plus the applicable fee must be returned before the transaction completes; otherwise, the transaction reverts. (aave.com)
Flash loans are primarily used for sophisticated on-chain strategies such as:
- arbitrage;
- collateral swaps;
- refinancing;
- liquidations;
- complex DeFi transactions.
They’re generally not designed for someone who simply wants to borrow money for a few months.
Is crypto lending tax-free?
Not universally.
In some jurisdictions, receiving genuine loan proceeds may not itself constitute taxable income because the borrower has an obligation to repay. U.S. federal tax guidance generally treats loan proceeds as excluded from gross income, subject to important exceptions such as debt forgiveness. (IRS)
But crypto-specific tax treatment can become complicated when collateral is transferred, sold, exchanged, liquidated, or used through a DeFi structure.
HMRC’s guidance shows exactly why blanket statements are dangerous: its treatment has depended on the legal and economic structure of the DeFi arrangement, and the UK introduced a new 2026 policy measure addressing certain cryptoasset lending and borrowing transactions. (GOV.UK)
So before using crypto lending specifically for tax planning, check the rules in your own jurisdiction and speak with a qualified tax professional.
Final Thoughts
Crypto lending is one of those DeFi concepts that sounds complicated until you strip it down to the basic exchange of capital.
Someone has assets. Someone else needs liquidity. The lending market connects them.
What makes crypto different is the infrastructure underneath that transaction.
A smart contract can hold collateral. An oracle can provide market prices. An interest-rate curve can respond automatically to utilization. A liquidation engine can protect lenders when collateral loses too much value. A lender can receive a tokenized representation of a lending position, such as an Aave aToken, instead of relying on a traditional bank statement. (aave.com)
That is the genuinely interesting part.
But I wouldn’t approach crypto lending by looking for the highest APY or the maximum borrowing limit.
I’d start with the opposite question:
What could make this position fail?
If you’re borrowing, look at your LTV, liquidation threshold, health factor, collateral volatility, and interest rate.
If you’re lending, look at utilization, liquidity, smart-contract history, oracle design, and where your yield actually comes from.
If you’re choosing between CeFi and DeFi, understand whether you’re trusting a company or a protocol-and recognize that both forms of trust have their own failure modes.
And if you’re thinking about crypto lending as a tax strategy, don’t assume that “loan = tax-free.” The treatment depends heavily on jurisdiction and transaction structure, with rules evolving quickly. The UK’s 2026 cryptoasset-loan policy changes are a good example of how quickly this area can develop. (GOV.UK)
The biggest mistake is treating crypto lending as free money.
It isn’t.
At its best, crypto lending is a flexible financial primitive that lets you turn idle digital assets into productive capital or unlock liquidity without immediately selling your long-term holdings. At its worst, excessive leverage, falling collateral prices, poor liquidity, bad oracle design, or weak protocol security can turn a seemingly attractive yield strategy into a very expensive lesson.
If you understand the mechanics first-collateral, LTV, utilization, interest, health factor, liquidation, oracles, and counterparty risk-the rest of the market becomes much easier to navigate.



