

Turning Idle Crypto into Productive Assets
If you’ve held cryptocurrency for any length of time, you’ve probably encountered a slightly strange idea: why should your coins just sit in your wallet when they could be helping secure a blockchain and earning rewards at the same time?
That’s essentially where staking comes in.
At the simplest level, crypto staking means committing tokens to a blockchain that uses Proof-of-Stake (PoS) so those tokens can participate, directly or indirectly, in the network’s consensus process. In return, the protocol may distribute rewards to participating validators and delegators. Ethereum, for example, describes Proof-of-Stake as a system in which validators deposit ETH as economic collateral and can lose some or all of that collateral if they act dishonestly. (ethereum.org)
I think the easiest way to understand staking is to stop thinking of it as a bank account.
You’re not simply handing your crypto to a company and collecting interest.
Instead, you’re participating in the economic machinery that keeps a blockchain running.
That distinction matters because it changes how you should think about the return. A quoted APY isn’t free money, and it certainly isn’t guaranteed income. The actual result depends on the blockchain, issuance schedule, validator performance, fees, token price, lock-up or withdrawal rules, and-particularly with liquid staking or restaking-the additional protocols sitting between you and the underlying asset.
The basic staking picture
| Attribute | What it means |
|---|---|
| Underlying mechanism | Proof-of-Stake consensus |
| Primary purpose | Help secure and operate a blockchain |
| Reward source | Usually protocol issuance and/or transaction-related rewards |
| Common participation models | Solo, delegated, pooled, liquid, custodial |
| Main economic risk | The staked token can lose market value even while your token balance increases |
| Advanced forms | Liquid staking and restaking |
You can therefore have a situation where your staking balance grows while the dollar value of your portfolio falls. That’s one of the first things I would keep in mind before looking at an attractive APY.
If you stake an asset yielding 8% but that asset falls 40% against the dollar, the staking reward obviously doesn’t magically protect you from the underlying market.
That sounds obvious, but it’s surprisingly easy to forget when a staking dashboard puts a large percentage right in front of you.
How Proof-of-Stake Staking Works?

Proof-of-Stake vs. Proof-of-Work
To understand staking properly, you first need to understand what problem Proof-of-Stake is trying to solve.
A blockchain needs some way for distributed computers to agree on which transactions are legitimate and which version of the ledger should become the canonical one. Bitcoin’s Proof-of-Work approach does this through computational competition: miners expend electricity and computing resources to produce valid blocks.
Proof-of-Stake takes a different route.
Rather than proving that you’ve spent large amounts of computational energy, you demonstrate that you’ve committed valuable capital to the network. That capital becomes part of the economic security mechanism.
Ethereum’s documentation describes the basic idea quite clearly: validators stake ETH into the protocol, participate in checking and proposing blocks, and can have their stake destroyed if they engage in certain dishonest behaviors. (ethereum.org)
So, conceptually:
Proof-of-Work:
“I spent computational resources to earn the right to participate.”
Proof-of-Stake:
“I committed economic value that can be penalized if I behave dishonestly.”
That difference is much more important than simply saying that staking is “more energy efficient.”
The security model itself has changed.
On Ethereum, for example, validators vote on checkpoints, and finality is reached when votes representing at least two-thirds of the total staked ETH support the relevant checkpoints. Once finalized, reversing the chain would require economically destructive behavior involving a large amount of stake. (ethereum.org)
In other words, the blockchain isn’t trusting validators because they’re nice people. It’s creating a financial incentive structure where honest participation is rewarded and certain forms of dishonest behavior can become extremely expensive.
How validators actually participate
A validator is essentially a participant responsible for helping the network process and confirm blocks.
On Ethereum, validator duties include checking blocks, submitting attestations, and occasionally proposing blocks. The protocol organizes time into slots and epochs; Ethereum currently defines each slot as 12 seconds, with 32 slots making an epoch. (ethereum.org)
But here’s an important point: you don’t necessarily have to run a validator yourself to participate in staking.
That’s where different staking models start to emerge.
Solo staking
Solo staking is the most direct relationship with the blockchain.
You operate your own validator infrastructure, maintain the required software, manage your keys, monitor the machine, and remain responsible for its performance.
Ethereum currently requires 32 ETH to activate an individual validator, although a validator can hold more ETH depending on its withdrawal credentials and configuration. (ethereum.org)
This model gives you considerable control, but it also gives you considerable responsibility.
If your node goes offline, you can miss rewards and incur penalties. If you configure it incorrectly or engage in slashable behavior, the consequences can be much more serious.
For someone who enjoys running infrastructure, monitoring systems, and understanding how the protocol works under the hood, solo staking can be fascinating.
For everyone else, it can feel like turning your supposedly passive investment into a small IT operations job.
Delegated and pooled staking
Pooled staking exists largely because most people don’t want to operate blockchain infrastructure themselves.
Instead of running your own validator, you contribute assets to a staking pool or delegate to a validator or service provider, depending on how that particular blockchain works.
The economic idea is simple: many participants combine resources, while a smaller number of operators handle the technical work.
Ethereum itself does not natively provide delegation in the same way some other Proof-of-Stake networks do; third-party services have emerged to fill that role. Ethereum’s documentation distinguishes these services across a spectrum ranging from staking-as-a-service to fully custodial exchanges. (ethereum.org)
This gives you convenience, but convenience always comes with a trade-off.
You may be relying on:
- a validator operator;
- a smart contract;
- a staking protocol;
- an oracle system;
- a custodian; or
- some combination of these.
The more components involved, the more carefully you should understand where your actual risk sits.
Exchange staking
Exchange staking is the most familiar option for many newcomers.
You deposit or hold an eligible token on a centralized platform, choose its staking product, and the platform handles the underlying infrastructure.
From your perspective, the experience can be almost frictionless.
But there is a fundamental difference between staking through a non-custodial protocol and handing custody to a centralized exchange. In the latter case, you’re adding counterparty and custody risk on top of the ordinary risks of staking.
Even Binance’s own educational material notes that staking can involve risks including slashing, malicious attacks, and technical requirements, while exchange-based services can abstract some of that complexity away. (Binance)
Convenience isn’t inherently bad. You simply need to know what you’re exchanging for it.
Modern DeFi Evolution: Liquid Staking and Liquid Staking Tokens
Traditional staking has an obvious problem.
Your capital can become difficult-or sometimes impossible-to use elsewhere while it’s participating in consensus.
Imagine you hold 10 ETH and decide to stake it. Your ETH is now productive from a network-security perspective, but you may have limited flexibility depending on the chain and staking method.
What if you suddenly want to:
- trade it;
- provide liquidity;
- use it as collateral;
- borrow against it;
- move it into another DeFi protocol; or
- exit the position immediately?
That’s the capital-efficiency problem that liquid staking tries to solve.
Solving the lockup dilemma
Liquid staking protocols create a tokenized representation of your staked position.
Instead of simply seeing your ETH disappear into a staking contract, you receive another asset representing your claim on the underlying staked position.
Ethereum’s own documentation describes liquid staking pools as services that allow users to stake ETH and receive liquid staking tokens representing the value of that position. (ethereum.org)
The result is a much more flexible structure:
ETH → liquid staking protocol → LST
The LST can potentially be transferred, traded, supplied as collateral, or used in DeFi while the underlying ETH remains involved in staking.
That’s a major conceptual shift.
Your original asset is no longer simply “locked.” Instead, its economic exposure has been transformed into a token that can move through other parts of the crypto economy.
What is an LST?
LST stands for Liquid Staking Token.
One of the best-known examples is stETH, issued by Lido.
According to Lido’s documentation, staking ETH through Lido results in an equivalent amount of stETH, while the token itself can be transferred, traded, and used in DeFi applications. Its supply reflects deposited ETH together with staking rewards and potential validator penalties. (Lido Docs)
That gives you a useful mental model:
stETHis not simply “another version of ETH.”
It represents an underlying staking position.
This distinction becomes particularly important when you start using LSTs in more complicated DeFi strategies.
Why LSTs are powerful
Suppose you stake 10 ETH directly and your staking position cannot immediately be used elsewhere.
Your capital is productive, but relatively static.
Now imagine that the same position produces an LST.
You might be able to hold that LST while:
- earning exposure to staking rewards;
- supplying it to a lending market;
- using it as collateral;
- providing liquidity;
- trading it against other assets; or
- integrating it into another DeFi strategy.
That’s where the phrase capital efficiency starts to make sense.
You haven’t necessarily created additional underlying ETH. You’ve made the economic representation of your staked position more composable.
And composability is one of DeFi’s biggest advantages.
But an LST is not risk-free ETH
This is where I would be particularly careful.
When you hold native ETH, your primary asset exposure is ETH.
When you hold an LST, you now have exposure to:
- ETH itself;
- the staking protocol;
- smart contracts;
- validator infrastructure;
- oracle mechanisms;
- liquidity conditions; and
- the market relationship between the LST and ETH.
Lido itself notes that while stETH can be redeemed at a 1:1 ratio under the protocol’s withdrawal mechanism, there can be rare circumstances in which the market or redemption relationship does not remain exactly 1:1. (Lido Docs)
That last point matters.
A liquid staking token can trade below its theoretical underlying value.
If you urgently need to sell stETH during a period of market stress and the available liquidity is thin, the market price may not perfectly match the value of the ETH represented by the token.
That’s the kind of risk that a simple “earn yield while staying liquid” slogan doesn’t capture.
The Next Frontier: Yield Stacking and Liquid Restaking

Liquid staking solved one major problem: how can I stake while keeping my capital usable?
Restaking asks a more aggressive question:
If my ETH is already securing Ethereum, can that same economic security help secure other systems as well?
That’s the basic idea behind restaking.
What is restaking?
EigenLayer is one of the most prominent protocols associated with this model.
Its core concept is to allow Ethereum’s existing economic security to be extended to additional services. Rather than every new decentralized service needing to bootstrap an entirely independent validator network and security budget, it can potentially leverage Ethereum’s staked capital through an additional set of economic commitments.
EigenLayer describes itself as infrastructure for shared, programmable security, while its documentation and whitepaper describe mechanisms through which restakers can opt into additional services and corresponding risks. (EigenLayer)
Those services are commonly referred to as Actively Validated Services, or AVSs.
An AVS might require operators to perform specific validation tasks. Restaked capital can then become part of the economic security behind those services.
At first glance, it sounds like an obvious win:
One asset secures multiple things, so perhaps one asset can generate multiple sources of rewards.
But that is also where the risk becomes more interesting.
Restaking is not “free extra yield”
Let’s say your ETH is already staked.
You then turn it into an LST.
Then you deposit that LST into a restaking protocol.
Then an operator uses your restaked position to participate in an AVS.
Your economic stack now looks something like this:
ETH
↓
Ethereum staking
↓
Liquid staking token
↓
Restaking
↓
AVS participation
Each additional layer can potentially introduce another reward source.
But each additional layer can also introduce another failure mode.
EigenLayer’s whitepaper explicitly discusses slashing mechanisms for restakers participating in AVSs, including the possibility that a restaker’s ETH could become subject to slashing if the relevant conditions are met. (EigenCloud)
So when you see a strategy advertising multiple layers of yield, don’t just add the percentages together and celebrate.
You should also add the layers of risk.
What are LRTs?
The next evolution is the Liquid Restaking Token, or LRT.
An LRT is broadly a liquid representation of a restaked position.
The basic conceptual flow is:
ETH → staking → LST → restaking → LRT
The appeal is obvious.
You potentially maintain exposure to:
- base staking rewards;
- restaking-related rewards;
- protocol incentives; and
- additional DeFi opportunities using the liquid representation.
But the structure is also considerably more complex than ordinary staking.
An LRT can depend on multiple protocols, operators, contracts, reward mechanisms, and market relationships. The result may be powerful capital efficiency, but it isn’t equivalent to simply holding ETH and earning a single staking reward.
That’s an important distinction for anyone evaluating APY.
Why Staking APY Can Be Misleading
Let’s talk about yield for a moment because this is where many staking articles become unnecessarily simplistic.
You’ll often see a number such as:
“Stake ETH and earn 4% APY.”
The number looks precise.
The underlying reality usually isn’t.
A staking yield can change because of:
- the total amount of assets being staked;
- validator participation;
- protocol issuance;
- transaction activity;
- MEV-related rewards;
- validator fees;
- commission structures;
- penalties;
- token price;
- incentive programs; and
- the specific platform you’re using.
So I wouldn’t treat APY as a fixed interest rate.
Think of it more as a current estimate of the reward rate under a particular set of network conditions.
That distinction becomes even more important with liquid staking and restaking because promotional yields may combine several different reward sources.
For example, a displayed “total yield” might include:
| Yield component | What it may represent |
|---|---|
| Base staking reward | Rewards from securing the underlying PoS network |
| Restaking reward | Compensation for providing additional economic security |
| Protocol incentives | Temporary or ongoing token incentives |
| DeFi yield | Returns generated by lending, liquidity provision, or other strategies |
| MEV-related income | Additional validator or protocol-level rewards where applicable |
These are not interchangeable.
A temporary token incentive is economically different from a native protocol reward.
A lending return is different again.
And an LRT strategy combining several of these can produce a headline APY that looks impressive while simultaneously exposing you to considerably more smart-contract and market risk.
Managing Risks: Slashing, Lockups, and Depegging
Staking isn’t a magic button that turns crypto into guaranteed passive income.
The risks are real, and understanding them is arguably more important than understanding the reward percentage.
Slashing penalties
Slashing is one of the most important concepts in Proof-of-Stake.
It is a penalty mechanism designed to punish certain validator behaviors that threaten consensus.
On Ethereum, slashable behavior includes proposing two different blocks for the same slot, making contradictory attestations, and related forms of provably conflicting consensus behavior. A slashed validator can lose ETH and be forcibly removed from the validator set. (ethereum.org)
There’s an important nuance here.
Not every validator mistake results in dramatic slashing.
Ethereum distinguishes between ordinary inactivity penalties and slashable offenses. Simply being offline can result in missed rewards and penalties, while specific provable forms of malicious or conflicting behavior can trigger slashing. (ethereum.org)
This matters because “staking risk” is often discussed as though all penalties are identical.
They’re not.
Validator downtime
A validator needs to participate reliably.
If it repeatedly goes offline, it may lose rewards or incur penalties.
For someone running their own validator, that means hardware reliability, internet connectivity, client configuration, software updates, key management, and monitoring all become part of the staking equation.
That’s why staking isn’t completely passive when you’re operating infrastructure yourself.
The blockchain may distribute rewards automatically, but someone still has to keep the validator healthy.
Smart-contract risk
When you use a staking pool, LST, or restaking protocol, you may introduce smart-contract risk.
A smart contract can contain a vulnerability.
An oracle can malfunction.
An upgrade can introduce unexpected behavior.
A protocol dependency can fail.
A bridge can be exploited.
The more sophisticated the strategy, the more difficult it becomes to identify every dependency.
This is one reason I would distinguish between:
staking risk
and
staking-platform risk.
They are related, but they’re not the same thing.
Lockups and withdrawal queues
Native staking can also create a liquidity problem.
Depending on the blockchain, exiting a validator may involve a waiting period or withdrawal queue.
Ethereum currently allows validators to exit and withdraw, but the timing can depend on network demand and the relevant queue. (ethereum.org)
That means you shouldn’t stake money that you know you may need tomorrow.
If your financial plan requires immediate access to the funds, locking them into a consensus system can be a poor fit even if the quoted yield looks attractive.
Liquid staking addresses part of this problem by providing a tradable representation of the position, but that introduces another risk: the liquid token can trade away from its underlying value.
LST and LRT depegging
This is one of the easiest risks to underestimate.
Suppose an LST theoretically represents one ETH.
That doesn’t guarantee the token will trade at exactly one ETH on every exchange, in every market condition.
If liquidity dries up or market participants become concerned about a protocol, the token can trade at a discount.
You might therefore have a situation where:
underlying ETH value = 1 ETH
but
market value of the LST = 0.97 ETH.
That doesn’t automatically mean the protocol has failed. It can simply reflect temporary market liquidity or redemption constraints.
Still, if you’re forced to sell during that period, the difference matters.
Restaking adds another risk layer
With restaking, you have to consider the underlying Ethereum staking risk plus the risks created by the additional service.
EigenLayer’s own whitepaper explains that restakers may be exposed to slashing when they participate in AVSs and that different combinations of services can create different risk profiles. (EigenCloud)
So the phrase “double yield” can be misleading.
You’re not necessarily getting something for nothing.
You’re being compensated for taking on additional economic responsibilities.
Choosing a Staking Model
If you’re trying to decide how to stake, I wouldn’t start with the highest APY.
I’d start with the question:
How much complexity and risk am I actually comfortable taking?
A useful framework looks like this:
| Staking approach | Control | Complexity | Liquidity | Additional risks |
|---|---|---|---|---|
| Solo staking | High | High | Lower | Infrastructure, validator penalties |
| Staking service | Medium | Medium | Varies | Operator and service risk |
| Pooled staking | Medium/Low | Low | Medium | Protocol and smart-contract risk |
| Liquid staking | Medium/Low | Medium | High | LST depeg and protocol risk |
| Restaking | Lower | High | Varies | Additional slashing and protocol exposure |
| LRT strategies | Lower | Very high | High | Multiple layers of smart-contract and market risk |
| Exchange staking | Low | Very low | Varies | Custody and counterparty risk |
There isn’t one universally correct model.
If you’re technically capable and want maximum control, solo staking can make sense.
If you simply want exposure to staking without maintaining infrastructure, pooled or delegated approaches may be more practical.
If capital efficiency matters, liquid staking becomes interesting.
And if you’re deliberately seeking additional yield and understand the additional risks, restaking can be explored-but I wouldn’t treat it as the natural next step for every beginner.
How I Would Think About Staking as a Beginner
If you are completely new to staking, I would keep the first step boring.
That’s actually a good thing.
Start by answering these questions:
What asset am I staking?
You need to understand the token itself before you worry about yield.
Why does this blockchain use staking?
If you don’t understand the consensus model, you don’t really understand what you’re earning rewards for.
Where do the rewards come from?
Are they protocol issuance, transaction fees, MEV, incentives, or some combination?
Can I withdraw whenever I want?
Don’t assume the answer is yes.
Who controls my assets?
Are you holding the keys, or is a company holding them for you?
What can cause me to lose money?
Look specifically for slashing, smart-contract bugs, depegging, withdrawal queues, and market volatility.
Only after answering those questions would I look at APY.
That order matters.
A high yield attached to an asset or strategy you don’t understand isn’t necessarily an opportunity. Sometimes it’s simply compensation for risk you haven’t noticed yet.
Staking vs. Holding: What Are You Actually Giving Up?
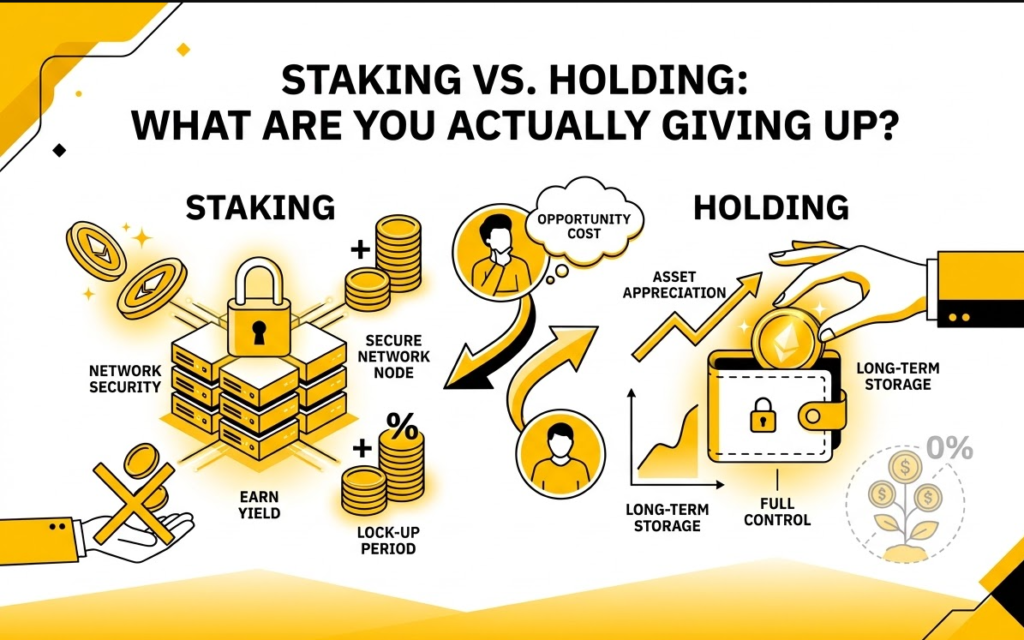
Holding a token in your wallet is simple.
You own it.
You can generally transfer it whenever you want, subject to network conditions and transaction costs.
Staking introduces a second dimension: productive participation.
You’re asking your capital to do something.
That can generate rewards, but it also means your assets may become subject to protocol rules.
The trade-off can be summarized like this:
| Holding | Staking |
|---|---|
| Maximum simplicity | More complexity |
| Usually immediate liquidity | Potential withdrawal restrictions |
| No staking reward | Potential protocol rewards |
| No validator responsibility | Validator/protocol exposure |
| Direct asset exposure | Asset + staking infrastructure exposure |
Neither approach is automatically superior.
Sometimes the simplest strategy is exactly what you need.
If you know you’ll need your funds soon, liquidity may matter more than staking rewards. If you’re holding a PoS asset for years and understand the mechanics, staking may make economic sense.
Why Liquid Staking Changed DeFi
Before liquid staking became widespread, staking and DeFi often competed for the same capital.
You could stake your ETH and help secure the network.
Or you could keep your ETH liquid and use it in DeFi.
Liquid staking blurred that distinction.
You could stake the underlying asset and receive a tokenized representation that remained usable elsewhere.
Lido’s documentation explicitly describes stETH as a liquid ERC-20 token that can be transferred, traded, and used in DeFi applications while representing staked ETH. (Lido Docs)
That composability created an entirely new design space.
Instead of:
ETH → staking
you could potentially have:
ETH → staking → LST → lending → liquidity → additional DeFi strategy
And that is exactly why liquid staking became such an important primitive in DeFi.
But there’s a catch that is worth repeating:
Composability multiplies both opportunity and risk.
Every new protocol you connect to can potentially introduce another smart contract, oracle, liquidity pool, or governance dependency.
Restaking: Where Staking Starts Getting Complicated
Restaking is fascinating because it changes the meaning of blockchain security.
Traditionally, a new decentralized service has to build its own validator network or security mechanism.
That can be difficult.
You need operators.
You need capital.
You need incentives.
You need a way to discourage malicious behavior.
Restaking proposes another model: leverage an existing pool of economically committed capital.
EigenLayer’s stated objective is to extend Ethereum’s economic security to additional services through a shared-security framework. (EigenLayer)
That can potentially make it easier for new services to bootstrap security.
But from your perspective as a restaker, it means your assets are now being asked to do more than one job.
And every additional job comes with additional conditions.
That’s why I would think of restaking less as “staking 2.0” and more as a new risk-management layer built on top of staking.
The rewards are only half the story.
The other half is understanding exactly what you’re agreeing to secure.
FAQ
What is crypto staking in simple terms?
Crypto staking is the process of committing cryptocurrency to a Proof-of-Stake blockchain so it can participate in network security and consensus, with participants receiving rewards in return. On Ethereum, for example, validators stake ETH as economic collateral and perform duties such as proposing and attesting to blocks. (ethereum.org)
Think of it this way: instead of simply holding your coins, you’re putting them to work as part of the blockchain’s security system.
The important caveat is that staking rewards are not guaranteed investment returns. The underlying token can fall in value, and depending on how you stake, you can also face validator, smart-contract, liquidity, or custody risks.
What is the difference between standard staking and liquid staking?
Standard staking generally means that your cryptocurrency is committed directly to a Proof-of-Stake network or staking system, potentially creating withdrawal or liquidity restrictions.
Liquid staking adds a tokenized representation of your staking position.
For example, Lido’s stETH represents ETH staked through its protocol and can itself be transferred, traded, or used in DeFi. (Lido Docs)
So the simplest distinction is:
Standard staking:
Your capital participates in staking.
Liquid staking:
Your capital participates in staking and you receive a liquid token representing that position.
That extra flexibility is useful, but it isn’t free. You’re taking on the risks associated with the liquid staking protocol and the market for its token.
What are the main risks involved in staking crypto?
The main risks depend on how you stake, but they can include:
- Market risk: the cryptocurrency itself loses value.
- Validator risk: poor performance can reduce rewards or result in penalties.
- Slashing: certain dishonest or conflicting validator behavior can destroy part of the staked capital. Ethereum documents specific slashable behaviors and their penalties. (ethereum.org)
- Smart-contract risk: a staking or DeFi protocol can contain exploitable code.
- Liquidity risk: withdrawals may involve queues or waiting periods.
- LST depeg risk: a liquid staking token can trade below the value of its underlying asset.
- Custody risk: centralized staking services add counterparty exposure.
- Restaking risk: additional services can introduce additional slashing and operational conditions.
The important takeaway is that staking risk isn’t one single thing.
It is a collection of different risks depending on the route you choose.
What is crypto restaking?
Crypto restaking is a mechanism that allows already-staked assets-or representations of those assets-to be used to help secure additional decentralized services.
EigenLayer is a prominent example. Its architecture allows Ethereum’s economic security to be extended to additional services, including Actively Validated Services, while restakers can take on additional responsibilities and corresponding risks. (EigenLayer)
The attraction is capital efficiency: the same economic stake can potentially support more than one security system.
The trade-off is equally important: more security responsibilities can mean more ways for that stake to be penalized or exposed to technical failure.
What are LSTs and LRTs?
An LST, or Liquid Staking Token, represents a staked position while remaining transferable. stETH is a well-known example. (Lido Docs)
An LRT, or Liquid Restaking Token, generally represents a position that has gone one step further into restaking.
A simplified progression looks like:
Native asset → staking → LST → restaking → LRT
Each step can increase capital efficiency and composability, but it can also add another layer of protocol and market risk.
Do I need 32 ETH to stake Ethereum?
You need 32 ETH to activate your own Ethereum validator. (ethereum.org)
However, you do not necessarily need 32 ETH to participate in Ethereum staking.
Pooled and liquid staking services allow users with smaller amounts to participate by combining capital with other users. Ethereum’s staking documentation explicitly describes pooled staking as a way for people with less than the 32 ETH validator requirement to participate. (ethereum.org)
The trade-off is that you’re introducing a third party or smart-contract protocol between yourself and direct validator operation.
Can staking really be called passive income?
It can be described as a source of passive crypto rewards, but I would be careful with the phrase “passive income.”
If you operate a validator yourself, there is technical work involved.
If you use a staking service, you’re relying on someone else.
If you use liquid staking, you’re taking on protocol and market risks.
And in every case, the value of the reward is ultimately tied to a volatile crypto asset.
So while staking can generate rewards without you actively trading every day, it isn’t equivalent to a guaranteed interest-bearing bank deposit.
Is a higher staking APY always better?
No.
A higher APY can reflect:
- higher protocol inflation;
- temporary token incentives;
- additional risk;
- lower liquidity;
- higher smart-contract exposure;
- validator performance assumptions; or
- a combination of several yield sources.
I’d much rather understand why a protocol pays 12% than simply see 12% and assume it’s better than 5%.
That single habit can save you from a lot of bad decisions in DeFi.
The Bottom Line
Staking is one of the most important mechanisms in modern crypto because it connects capital, network security, and economic incentives.
At the basic level, Proof-of-Stake asks users to commit valuable assets so validators can participate in consensus. Ethereum is a clear example: validators stake ETH, perform consensus duties, receive rewards for correct participation, and can be penalized for certain failures or dishonest behavior. (ethereum.org)
Then came liquid staking, which addressed a major weakness of traditional staking by turning staked positions into transferable tokens. stETH is a good illustration: it represents staked ETH while remaining usable across the broader DeFi ecosystem. (Lido Docs)
And then came restaking, which pushes the concept further by allowing already-staked capital to contribute to the security of additional services. EigenLayer’s model demonstrates both the attraction and the complication of this approach: capital becomes more productive, but the associated responsibilities and risk surface also expand. (EigenLayer)
If you’re just getting started, I wouldn’t rush straight toward the most complicated strategy you can find.
Start with ordinary staking. Understand where the reward comes from. Learn how validators work. Check whether your funds are locked. Understand the withdrawal process. Then, if liquid staking makes sense for your situation, learn how LSTs work before moving on to restaking or LRTs.
The basic principle is surprisingly simple:
Don’t chase the yield before you understand the risk that produces it.
Once you understand that, staking becomes much easier to evaluate-and you can decide whether the additional rewards are actually worth the additional complexity.



